

Rain Instant Pay
4.7

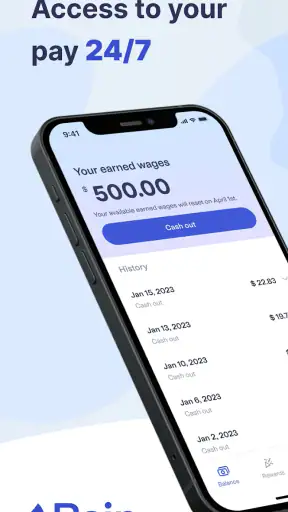
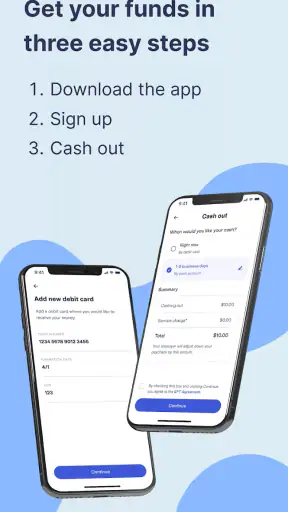
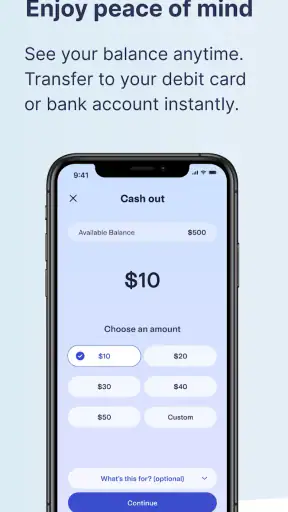
Getting paid on your normal payday is simple until an unexpected bill arrives in the middle of the week. Rain Instant Pay is a business app built around that problem: it helps eligible employees access employer benefits through an early-pay service rather than waiting for the usual payroll date. I found its appeal easy to understand, but its usefulness depends heavily on whether your employer participates and whether taking money early actually improves your situation.
Rain Technologies Inc developed the app, which is available free of charge and carries an Everyone age rating. It belongs in the business category, although its practical purpose is personal: giving workers another way to manage earned income. The app has reached over 500 thousand installs and holds a 4.7 average from roughly 34 thousand ratings, with around 4 thousand written reviews. Those figures suggest that many users find the basic idea useful, but they should not be mistaken for a guarantee that the service will fit every payroll arrangement.
How Rain Instant Pay fits into everyday money management
Free access does not mean universal access
The clearest cost point is that the app itself is free. I can install it without paying an upfront purchase price, which makes trying it less risky than signing up for a paid budgeting product. That is the part of the value equation that is easy to verify: there is no stated app purchase cost standing between a worker and the initial setup.
However, “free” should be read carefully here. Rain Instant Pay is not a general-purpose bank account or a universal paycheck tool that automatically works for anyone with a job. Its purpose is tied to employer benefits, so access depends on an eligible workplace arrangement. The app can be free to download and still be irrelevant if your employer is not supported. Before spending time on registration, I would first check whether your workplace offers Rain and whether your employment details match the participating arrangement.
I also would not treat the free label as proof that every possible transaction or service connected with early pay has no cost. The app’s price and the cost of using a particular benefit are separate questions. Since the practical terms can depend on the employer setup and the action you choose, I would read the in-app explanation carefully before confirming an advance. That habit matters more than the download price.
What the app delivers when the arrangement fits
Rain Instant Pay is most valuable when it gives you access to money you have already earned before your regular payday. That can be a meaningful distinction from a conventional loan. Instead of applying for a new credit product, a worker may be using an employer-linked benefit connected to current wages. Still, I would keep the distinction practical rather than assuming that early access is automatically harmless: money received now will affect what remains available later.
The app’s strongest use case is a short gap between an urgent expense and payday. Imagine a car repair appears after several days of work, while the next paycheck is still some distance away. If your employer supports Rain, the app may give you a way to handle that immediate pressure without putting the repair on a credit card or asking a friend for help. The benefit is not that the expense disappears; it is that the timing becomes more manageable.
That timing feature can also help with smaller problems that are expensive when ignored. A late utility payment, a necessary prescription, or a grocery shortage can create fees and stress out of proportion to the amount involved. In those situations, early access may be useful because it addresses a cash-flow problem rather than requiring a long-term borrowing decision.
My practical advice is to use the app as a bridge, not as a second payday. Before requesting money, I would write down the amount needed, the date of the normal paycheck, and the bills that paycheck must cover. This simple check reveals whether Rain is solving a temporary mismatch or merely moving the same shortage forward.
A workflow that rewards planning
The most useful way to approach the app is to make it part of a weekly money check rather than opening it only during a crisis. After checking your account balance, list fixed bills, food, transport, and any automatic payments due before payday. Then decide whether an early-pay request would cover a specific need. Giving the money a job reduces the risk of spending it casually because it arrived earlier than expected.
I would also avoid requesting the maximum amount simply because the option appears available. A smaller amount can solve the immediate issue while leaving more of the regular paycheck intact. This is one of the less obvious trade-offs of instant-pay services: convenience can make the available balance feel like extra income, even though it is still connected to the same pay cycle.
Another sensible habit is to keep a record of every early transfer in a note or budget app. That record makes the next payday easier to predict and helps identify a pattern. If you need Rain repeatedly for groceries or ordinary bills, the underlying issue may be an income-versus-expenses problem that the app cannot repair. In that case, a conventional budget review, a payroll conversation, or a longer-term financial solution may be more useful.
Where it differs from the usual alternatives
Compared with a credit card, Rain Instant Pay can be appealing because its central idea is access to earned pay rather than revolving credit. A credit card remains useful for purchases that require card acceptance, purchase protections, or a longer repayment plan, but it can also make an emergency more expensive if a balance carries forward. Rain is more focused: it addresses the timing of income, not broad borrowing or spending.
Compared with a traditional personal loan, the app is lighter and more immediate in concept. A loan is designed around borrowing a defined amount and repaying it under agreed terms. Rain is aimed at an employer benefit connected with pay. That makes it a poor replacement for funding a large, planned expense, but a potentially better fit for a short cash-flow gap if the workplace arrangement allows it.
Compared with a standard budgeting app, Rain does something different. A budgeting tool helps you plan money you already have and anticipate future bills; it does not necessarily change when wages become available. Rain can complement a budget, but it cannot replace one. In fact, using both approaches together makes more sense than relying on early pay alone: the budget shows whether the request is necessary, while Rain may address the timing problem.
A savings account is the healthiest alternative when you have enough time to build an emergency cushion. Savings gives you a separate reserve and avoids repeatedly drawing from future wages. Rain becomes more compelling when that reserve is not yet available and the expense cannot reasonably wait. The trade-off is that savings protects future pay, while instant pay shifts access forward.
Important friction before the first request
The first question I would ask is not “How fast can I get money?” but “Is my employer arrangement active?” Because the app is designed around employer benefits, eligibility is central to the experience. Someone downloading it independently may discover that installation alone does not unlock the service. That is not a flaw in the app’s basic purpose, but it is an important expectation to set before relying on it for an urgent bill.
I would also make sure my employment information is entered consistently with payroll records. Small differences in names, contact details, or workplace information can create avoidable setup friction in any employer-linked service. If your employer recently changed payroll providers, your hours are irregular, or you have more than one job, I would be especially cautious about assuming that the displayed information represents your complete financial picture.
Irregular workers should think carefully about timing. Someone with stable hours may find it easier to estimate what will remain on payday. Someone whose shifts change from week to week has less certainty and may be more likely to overestimate the next payment. For that user, an early-pay request should be conservative, with room for changes in hours, deductions, or ordinary expenses.
The app is also not a substitute for speaking with payroll when a paycheck is wrong. If the problem is missing hours, an incorrect deduction, or a delayed payment, an instant-pay request may hide the symptom without correcting the cause. I would contact the employer for payroll errors and use Rain only for the cash-flow need it is actually designed to address.
Who is likely to get real value
Rain Instant Pay makes the most sense for an employee whose workplace offers the benefit, whose income is generally predictable, and who occasionally faces expenses before payday. That includes people dealing with a one-off repair, a necessary household purchase, or a bill whose due date does not line up with their pay schedule. For them, the app can be a practical safety valve.
It may also suit someone who has no emergency savings yet but wants an alternative to immediately using a credit card. I would still compare the consequences of each choice, but the app’s employer-linked focus can feel more relevant than applying for a broad loan when the need is temporary and tied to the current pay cycle.
The best users are disciplined about amounts and dates. They know exactly why they need the money, understand what the next paycheck must cover, and can resist treating early access as a permanent increase in income. Used that way, the free app can deliver meaningful convenience without becoming the center of the household budget.
Who should probably skip it
I would skip Rain Instant Pay if my employer does not participate, since the app’s usefulness depends on that connection. I would also avoid making it part of my routine if I already struggle to cover regular expenses from one payday to the next. Repeated early access can make the calendar feel easier today while making the next pay period tighter.
It is not the right tool for a large purchase, long-term debt, or an investment decision. A personal loan, structured savings plan, employer payroll discussion, or professional financial guidance may be more appropriate depending on the situation. The app addresses timing; it does not turn an unaffordable expense into an affordable one.
People who prefer a complete spending overview may also find that a dedicated budgeting app is more important. Rain can help with access, but it is not the same as tracking categories, building savings goals, or understanding recurring subscriptions. I would not choose it as my only financial app if my main goal were broader money management.
What the current release tells me
The current version is 2.7.1, and the app was released on February 1, 2020. That history matters because it shows this is not a brand-new concept being tested for the first time. The strong user response and substantial install base also make it easier to view Rain as an established option in its niche rather than an experimental download.
Even so, an established app still deserves ordinary caution. I would keep the app updated, review each screen before confirming a request, and avoid making decisions based only on a prominently displayed available amount. The most important information is the practical effect on the next payday, not how convenient the current balance looks.
I would also separate popularity from suitability. A 4.7 average and a large body of user feedback are encouraging signs, but they cannot tell me whether my employer is supported, whether my pay pattern is predictable, or whether early access will improve my particular budget. Those are personal checks I need to make before relying on the service.
My verdict on the free value
Rain Instant Pay offers clear value when three conditions meet: the employer benefit is available, the need is genuinely short term, and the user plans the next payday before taking money early. In that situation, free access to an employer-linked instant-pay option can be more useful than turning a small timing problem into card debt or a formal loan application.
The trade-off is equally clear. Convenience can encourage repeated use, and early money is still connected to future income. The app should therefore be treated as a controlled bridge for specific expenses, not as permission to spend beyond a sustainable budget. That distinction is the difference between using the service thoughtfully and depending on it.
My recommendation is to try it if your employer offers Rain and you occasionally need help with the timing of earned pay. I would skip it if you want a full budgeting system, need long-term borrowing, or already rely on advances to cover ordinary living costs. Since the app is free, the initial download carries little purchase risk, but the meaningful decision comes later: whether the benefit improves your cash flow without weakening the paycheck that follows.
For the right worker, that is a worthwhile and specific job for a business app. For everyone else, a savings habit, a budgeting tool, or a direct payroll conversation may provide more lasting value. I like Rain Instant Pay best when it stays in its lane: a carefully used option for an employer-linked cash-flow gap, with the user keeping full control of the larger plan.
4.7
4.22K Reviews
Pros
- Fast access to earned wages after eligible shifts
- Simple interface makes payment requests easy to manage
- Helpful for handling unexpected expenses between paydays
- Works with participating employers and payroll systems
- Clear transaction history helps track advances and repayments
Cons
- Availability depends on employer and payroll provider participation
- Fees may apply depending on the advance or transfer option
- Not all earnings may qualify for instant payment
- Frequent advances could make budgeting more difficult
- Support response times may vary during busy periods


